The Fuel Shock That Is Rewriting Every Freight Budget
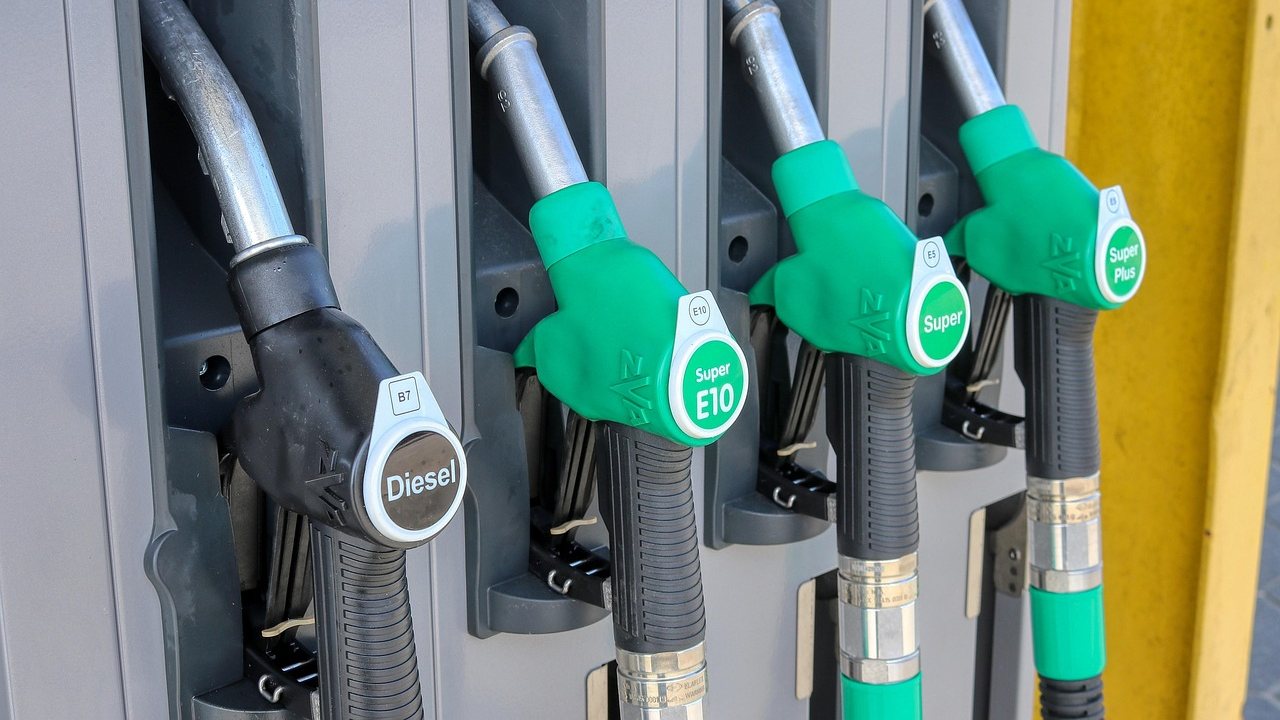
Every importer working through Q4 plans right now is dealing with a number that was unthinkable twelve months ago. U.S. on-highway diesel reached $6.285 per gallon for the week ending September 14, 2026 — a new all-time record in a data series that the Energy Information Administration (EIA) has tracked continuously since 1994. That is $2.55 more per gallon than the same week last year, a year-over-year surge of roughly 68 percent. Diesel is not a line item most importers think about directly, because they are not putting it into trucks themselves. But it is embedded in every fuel surcharge, every drayage invoice, every last-mile delivery fee, and every refrigerated transport bill that crosses their desks. Understanding exactly what is driving this shock — and how to manage around it — is now a core logistics competency, not an afterthought.
Two Wars, One Refining Crisis
The record at the pump did not begin at the pump. It began at two conflict zones on opposite sides of the Eurasian landmass, each of which has independently removed massive quantities of refined diesel from global markets.
The primary driver is the Strait of Hormuz. The International Energy Agency noted in its September Oil Market Report that around 15 million barrels per day of crude and another 5 million barrels per day of oil products — including diesel, jet fuel, and other middle distillates — normally transited that waterway before the conflict with Iran began in late February. Those flows have been severely constrained. Gulf country diesel and gasoil exports averaged roughly one-quarter of their pre-war volume in August, according to the IEA. Because the Persian Gulf collectively accounted for roughly one-third of global diesel export volumes in the prior year, that simultaneous disruption is systemic rather than regional.
The second driver is Ukraine's sustained drone campaign against Russian refining infrastructure. Since March, strikes have hit refineries at Saratov, Kirishi, Norsi, the Moscow refinery, Syzran, Novokuybyshevsk, Volgograd, Ryazan, and multiple other facilities. According to Capital Economics, approximately 40 percent of Russia's oil refining capacity is now offline, representing roughly 3 percent of global refining capacity removed from world markets. Russia, previously the world's second-largest seaborne diesel exporter, responded by banning diesel exports through at least January 2027 to protect its domestic supply. Reuters reported on September 15 that six of Russia's leading diesel-producing refineries — which together account for roughly half of the country's diesel production — had reduced or halted output following drone attacks.
Why Crude Prices Are Not the Whole Story
Many importers assume that if oil prices ease, diesel prices will follow quickly. The current situation breaks that assumption. Diesel's record does not need an oil-price shock to happen — crude sits near $100 a barrel, well below its inflation-adjusted highs, yet the cost of turning that barrel into diesel has blown out sharply. The crack spread, a measure of the refining margin between crude inputs and finished diesel output, spiked to approximately $100 per barrel in early September, against a historical norm well below $20. That spread is the real story: the tightness is in the refining layer, not in crude availability. U.S. distillate stocks sit approximately 13 percent below the five-year average. Even if Hormuz flows partially recovered, the refinery damage across multiple countries means the conversion infrastructure to produce diesel at scale is simply not there. Analysts broadly expect refining margins to remain well above historical norms through the end of 2026, with meaningful normalization unlikely under most scenarios before 2028.
How Fuel Surcharges Work — and Why They Lag
For importers, the immediate transmission mechanism is the fuel surcharge (FSC) embedded in trucking, drayage, and intermodal contracts. FSC is calculated by a standard formula: the current EIA weekly on-highway diesel average minus a contractual base price, divided by an assumed miles-per-gallon figure. Because most FSC programs update on a weekly cycle, carriers are often paying today's diesel prices while being reimbursed based on data from the prior week. When prices are climbing as rapidly as they have in September 2026 — the week-on-week move of $0.318 was among the sharpest recorded — that lag creates a growing gap between a carrier's actual cost per mile and the fuel recovery built into the rate. Carriers on quarterly surcharge resets face an even larger exposure window. For shippers, the practical consequence is that a spot-market rate quoted on Monday may reflect a different surcharge than the one on the final invoice if the diesel index rolls over mid-week. Reviewing the EIA reference date embedded in every freight contract and ensuring it aligns with current billing cycles is an immediate action item.
The Sectors Feeling It First and Hardest
Not all supply chains absorb the diesel shock equally. The impact is most visible in categories that are transport-heavy, move frequently, or rely on tight delivery windows. Food distribution sits at the top of that list. Diesel is integral to every stage of the food supply chain, powering farm equipment and fishing boats as well as the trains and trucks headed to distribution centers and grocery stores. The Independent Grocers Alliance, a grouping of 7,500 global supermarkets, estimates that fuel accounts for roughly 15 to 30 percent of the total cost of food. Items requiring refrigeration during transport are among the first to see price increases — and the data is already showing it. In July, overall U.S. grocery prices were up 2.7 percent compared to a year prior, but seafood prices were up 7 percent and fresh fruit prices were up 4.9 percent. As freight contracts reprice and fuel surcharges take hold on new agreements, more of these costs will work their way toward the consumer. Experts note that price shifts travel slowly through the food pipeline, meaning the worst consumer-facing impact from September's record diesel levels may still be weeks away.
Beyond food, the categories of building materials, retail general merchandise, and e-commerce fulfillment face compounding pressure. Amazon rolled out a 3.5 percent fuel and logistics surcharge on some third-party sellers earlier in the conflict. UPS, FedEx, and USPS have added fees on shipments citing rising fuel costs. For importers whose landed-cost models were built on 2025 diesel assumptions, those models require immediate recalibration.
The Regional Dimension: Not One Number
The national average masks significant regional variation that matters for importers routing freight from ports to final destinations. USDA data for the week ending September 7 showed California leading at $7.764 per gallon, the West Coast (excluding California) at $6.314, and the Central Atlantic averaging $6.051. The Lower Atlantic region was the most affordable at approximately $5.605. For a shipment arriving at the Port of Los Angeles versus one coming through Savannah or Miami, the drayage fuel surcharge component can differ by more than $1.50 per gallon of diesel consumed on the road leg. Importers with flexible port-of-entry choices who have not revisited their routing assumptions since January 2026 may find meaningful savings by rerunning total landed cost models that include current regional fuel prices rather than national averages.
What Importers Can Do Right Now
The refining crisis is structural rather than a passing spike, and waiting for prices to normalize before taking action is itself a costly decision. A set of concrete steps can limit exposure without requiring major supply chain redesign.
Audit Every Fuel Surcharge Clause
Pull every active domestic trucking, drayage, and intermodal contract and identify the EIA reference date and base-price assumption embedded in the FSC formula. Any base price set below $4.50 is generating a surcharge multiplier that is now significantly higher than it was when the contract was signed. Renegotiating FSC base prices or switching to weekly indexed adjustments reduces billing disputes and improves cost predictability.
Consolidate Shipments to Reduce Per-Unit Fuel Exposure
Full container load (FCL) moves and consolidated drayage runs distribute fuel surcharge costs across more units. Where cargo volumes allow, consolidating LCL moves into FCL or batching inland deliveries reduces the number of loaded miles per unit of freight. At $6.28 per gallon, every unnecessary deadhead or partial-load move carries a surcharge cost that was negligible twelve months ago.
Revisit Port-of-Entry and Modal Choices
For freight destined for inland locations, the interplay between ocean port selection and over-the-road drayage distance has become more consequential. A port closer to the final destination may carry a higher ocean freight rate but a materially lower total fuel surcharge on the inland leg. Run total landed cost comparisons — including current regional diesel rates — before committing to Q4 routings.
Hedge Forward Where Contracts Allow
For importers with long-term freight agreements, some carriers and brokers will negotiate fuel-price collars or fixed FSC arrangements for defined periods. Given analyst consensus that elevated diesel is unlikely to normalize before 2028, locking in a ceiling on surcharge exposure for the next two to three quarters has strategic value even if it comes at a modest premium to today's spot surcharge.
Watch the EIA Weekly Release Every Monday
The EIA publishes updated on-highway diesel figures every Monday. Building that number into weekly logistics planning — rather than treating it as background noise — ensures that procurement, operations, and finance teams are working from the same fuel-cost baseline when booking loads and reviewing invoices.
How ASR Can Help
At ASR WorldWide Express, we coordinate the full freight lifecycle for importers navigating this cost environment — from origin consolidation and ocean booking through port handling, customs clearance coordination via our trusted licensed customs broker partners, drayage, and final delivery. When fuel surcharges are climbing week by week, having a single freight forwarder managing the chain reduces the compounding effect of multiple surcharge layers from disconnected service providers. Our team actively monitors EIA diesel data, carrier FSC updates, and regional routing options to help clients keep total landed costs under control even as the underlying fuel market remains volatile.
Call us at +1 786 373 3003 or email shipping@asrwe.com to review your Q4 freight program against current diesel realities.
Important Disclaimer
This article is intended for general informational purposes only and does not constitute legal, financial, or customs compliance advice. Diesel prices, fuel surcharge formulas, carrier contract terms, and regulatory conditions change frequently. Importers and exporters should consult their licensed customs broker, freight forwarder, legal counsel, and financial advisors before making operational or contractual decisions based on the information presented here.