The Red Metal Is Rewriting Importer Cost Structures
Copper has become the defining trade story of 2026, and not because the global economy is booming. Copper remains up more than 47% year-to-date, driven by a collision of forces that no single factor can explain: a sweeping new Section 232 tariff, consecutive mine disruptions across three continents, and a speculative rush to load US warehouses ahead of further duties. For any business that imports wire, pipe, cable, connectors, electrical components, or the thousands of downstream products that depend on fabricated copper, the cost environment has fundamentally changed. Understanding the mechanics of what happened — and what comes next — is now a procurement and compliance priority, not an optional background read.
What the Section 232 Tariff Actually Covers
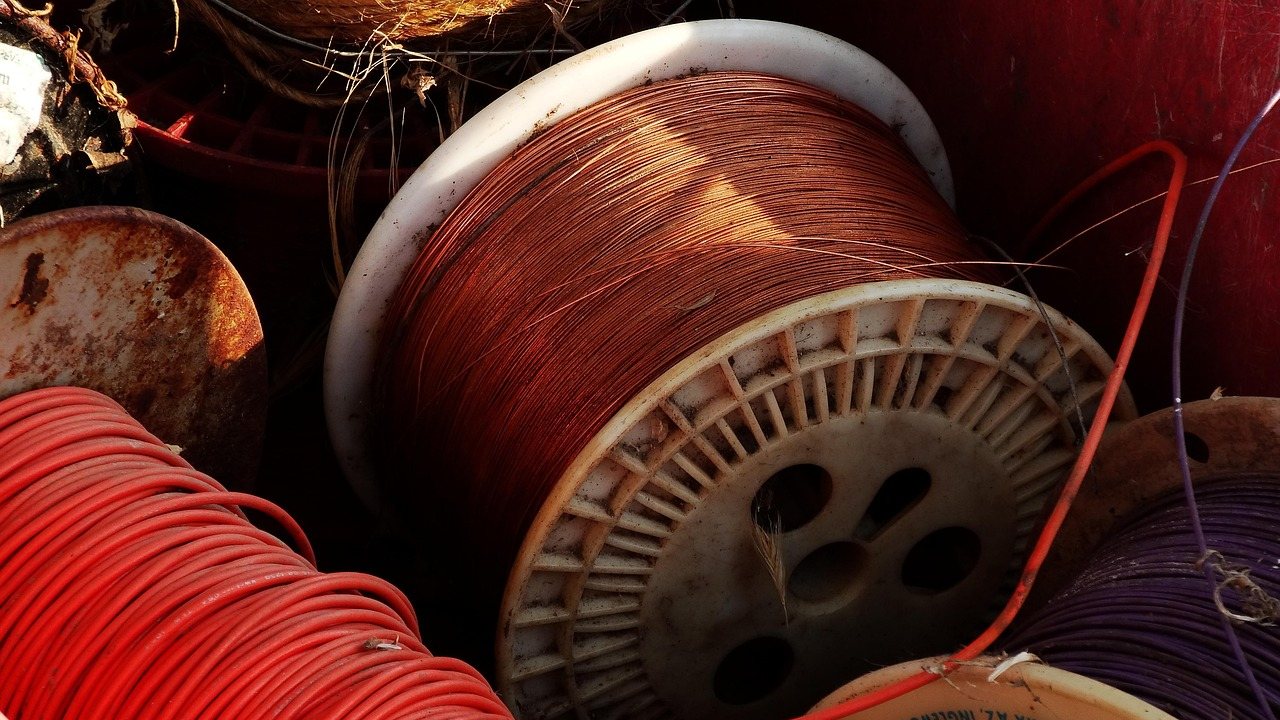
Starting August 1, 2025, President Trump imposed 50% tariffs on global imports of semi-finished copper products, including copper pipes, wires, rods, sheets, and tubes, and copper-intensive derivative products such as cables and connectors. The proclamation was aimed at addressing the implications of copper imports on national security, following a Section 232 investigation under the Trade Expansion Act of 1962.
President Trump did not impose Section 232 tariffs on copper input materials such as copper ores, concentrates, mattes, cathodes, and anodes, or copper scrap. Section 232 tariffs applied only to the copper content of a product, and non-copper content remained subject to other duties. That distinction matters enormously for importers classifying mixed-content goods.
In 2025, the United States imported $16.2 billion worth of copper products included in the April 2026 proclamation. Of that total, $7.2 billion came from semi-finished copper products, with 25% by value from the EU and 20% from Canada, and $9.0 billion from copper-intensive derivative products, with 31% by value from China and 26% from Mexico. No trading partner is exempt. Chile, Canada, Mexico, and Peru all pay it; FTA preferences do not reach the Section 232 layer.
April and June 2026: The Tariff Structure Tightened Further
The August 2025 proclamation was only the opening move. President Trump issued a sweeping proclamation on April 2, 2026, modifying the existing trade remedy tariff regimes on aluminum, steel, and copper products and derivative products. Section 232 duties now apply to the entire customs value of the imported product and are not based on the percentage of metal content. That shift closed a major loophole that importers of partially copper-intensive goods had relied on to soften the blow.
The proclamation established a tiered tariff structure: 50% on products made almost entirely of copper, steel, or aluminum; 25% on derivative products; 15% on metal-intensive electrical equipment through 2027; and 10% on products made abroad using American-sourced metals.
On June 1, 2026, President Trump signed a new proclamation further adjusting the Section 232 tariff regimes on aluminum, steel, and copper. Changes took effect June 8, 2026, through December 31, 2027. Targeted relief for key industries expanded eligibility for a reduced 15% tariff rate to include agricultural equipment, residential HVAC systems and components, and certain industrial machinery.
Importers must also note a new compliance obligation. Mandatory reporting of the primary country of smelt and country of cast, with an optional secondary country of smelt, is now required for copper articles under specific HTSUS codes, effective July 30, 2026. Misclassification or incomplete smelt-and-cast declarations now carry direct audit risk.
What Phase 2 Tariffs Could Mean: Refined Copper on the Clock
The President directed the Secretary of Commerce to provide an update on domestic copper markets, including refining capacity, by June 30, 2026. This report was intended to inform the President's determination on whether to impose phased tariffs starting in 2027 at 15% and increasing to 30% starting in 2028.
The Commerce Department's June 30, 2026, deadline to recommend whether to impose refined copper tariffs passed without an announcement. The decision remains pending, and traders have spent the year shipping copper into the United States ahead of a 15% duty on refined imports due in January 2027, rising to 30% in 2028, a trade that has dominated the paper market and drained warehouses everywhere else. Importers of refined copper cathodes — currently untariffed — should not assume that status is permanent.
Three Supply Disruptions Compounding the Tariff Shock
The tariff story would be consequential on its own. But it is unfolding against an extraordinarily tight physical supply backdrop. Codelco output in Chile declined 10%, BHP's Escondida fell 15.75%, and the Glencore-Anglo American Collahuasi joint venture declined 10.80%, reducing supply from the world's largest copper-producing country and reinforcing the 2026 global deficit outlook.
Chile produced 403,424 tonnes of copper in July, down 9.4% from a year earlier and 9.8% below June, the weakest July for the world's biggest producer since 2011. The national statistics agency blamed weather in the north of the country that hindered normal production, along with maintenance at major sites.
The Gresik smelter in Indonesia, which processes Grasberg concentrate, remains offline following a boiler leak on August 8. The Iran conflict has also disrupted roughly half of global sulphur supply, a critical input for SX-EW cathode production in Chile and Peru, while longer Cape of Good Hope routings are adding an estimated 20–30% to freight costs on affected trades. Supply disruptions on this scale mean that even if the tariff pressure eased tomorrow, the physical market would still be tight.
The COMEX Stockpile Divergence Every Importer Should Understand
The most visible consequence of tariff front-running is a historic split between US and non-US inventories. COMEX stockpiles reached about 688,000 tonnes on August 31, almost three times the LME total. Global copper inventories fell more than 95,000 metric tons in July as copper continued flowing into the United States. COMEX inventories rose by approximately 45,213 metric tons, while inventories at the London Metal Exchange and Shanghai Futures Exchange declined significantly.
A widening COMEX-LME spread is once again pulling metal across the Atlantic as US tariff speculation becomes a global tightening mechanism. What this means practically is that copper costs more outside the US than the headline COMEX price alone suggests, and domestic buyers who assumed they could draw on cheap overseas supply at any time are finding that window closed. The COMEX-LME spread is increasingly being read as a measure of tariff risk rather than a pure fundamentals signal.
Which Industries Are Being Hit Hardest
Copper is used in a variety of sectors, including construction, electronics, transportation equipment, energy infrastructure and technology, and consumer products. The tariff's reach is correspondingly broad.
Construction and infrastructure projects face direct cost increases on the most heavily tariffed product categories in plumbing, HVAC, and building services. Wire, cable, and connector producers relying on imported semi-finished copper inputs face significant margin compression or customer price increases. Modern EVs use substantially more copper per unit than internal combustion vehicles, amplifying tariff sensitivity across the entire EV growth sector. Both wind turbines and utility-scale solar facilities require extensive copper wiring, making the cost of electrification infrastructure materially sensitive to copper tariff policy.
According to the Associated Builders and Contractors, copper wire and cable costs have risen 83.7% since February 2020. The Section 232 tariff layer is not the only contributor, but it is the most recent and most structural one.
Copper is the second most widely used material by the U.S. Department of Defense and is essential for defense systems, aircraft, ships, vehicles, ammunition, and critical infrastructure such as the electric grid and telecommunications, with no sufficient substitutes for many applications. That strategic dependency is precisely why the administration framed the tariff as a national security measure.
Practical Steps for Importers Right Now
Given the current environment, importers of any copper-intensive goods should treat tariff compliance as an immediate operational priority across several dimensions.
Audit HTS Classifications Under the New Full-Value Rule
Section 232 tariffs now apply to the entire customs value of covered copper articles and their derivative products, regardless of actual metal content, eliminating prior valuation approaches that applied duties only to the metal portion of the article. Any entry strategy built on the old metal-content-only calculation is now incorrect and could trigger back-duty liability.
Verify Smelt-and-Cast Country of Origin
Stacked with Section 122 at 10% and Section 301 where applicable, Chinese copper articles can run 85% or higher effective duty. Knowing exactly where your copper was smelted and cast is no longer optional — it directly determines which tariff stack applies.
Explore the Domestic Content Rate
If at least 95% of the copper by weight used in your product is smelted in the United States, the tariff can be reduced to approximately 10% of total product value. For manufacturers sourcing domestically produced wire or rod, this threshold is worth evaluating carefully with a qualified advisor.
Review Annex III Relief for Electrical Grid Equipment
Certain metal-intensive industrial equipment and electrical grid equipment and derivative articles are subject to capped tariff rates at 15% through 2027. Importers bringing in grid-related equipment should confirm whether their products qualify for this relief before filing under the standard 50% rate.
Build Landed Cost Models That Assume the 50% Layer Persists
With a December 31, 2027, sunset on all temporary reductions, importers should audit their HTS classifications now to avoid overpaying or underpaying. The safest planning assumption is that the 50% rate on semi-finished copper remains in force through the end of 2027, with the possibility of refined copper duties arriving in January 2027 at 15%.
How ASR Can Help
Navigating the layered complexity of Section 232 copper tariffs — full-value calculations, smelt-and-cast reporting, derivative product inclusions, and stacking rules — requires precision at every step of the import process. ASR WorldWide Express coordinates customs clearance through trusted licensed customs broker partners who are actively tracking every proclamation update and CBP guidance notice in this space. We work with importers of copper products, electrical components, HVAC equipment, construction materials, and manufactured goods to ensure entries are classified correctly, documentation is complete, and duty exposure is understood before cargo moves.
If your supply chain touches copper in any form, now is the time to review your exposure with experienced hands. Call us at +1 786 373 3003 or email shipping@asrwe.com. FMCSA MC# 1667345-B | DOT# 4286843 | SCAC AZCB.
Important Disclaimer
This article is intended for general informational purposes only and does not constitute legal, tax, or customs compliance advice. Tariff rules, proclamation annexes, HTS classifications, and CBP guidance change frequently. Importers should consult a licensed customs broker and qualified trade counsel to assess the specific impact of Section 232 copper tariffs on their shipments before making any procurement or compliance decisions.